
Key Takeaways
Your investment strategy should evolve as your income, responsibilities, financial goals and time horizon change. Starting early can give your investments more time to compound, while later stages of life may require greater attention to retirement planning, capital preservation and income generation. The right strategy is not determined by age alone. Your risk tolerance, financial responsibilities, existing wealth and investment goals also play an important role.
Investment Strategy for Different Life Stages: Your 20s, 30s, 40s and 50s
Imagine receiving your first salary.
You look at the amount credited to your bank account and suddenly realise that you have something you did not have before: the ability to make independent financial decisions.
You may think about buying a phone, travelling, upgrading your lifestyle or simply enjoying your first income. Investing for retirement may feel like something that belongs to a much older version of you.
But this is where the investment journey can begin.
The interesting thing about investing is that your financial strategy does not remain the same throughout your life. The person investing at 25 may have completely different priorities from someone investing at 35. At 45, retirement planning may become much more important, while at 55, the focus may increasingly shift toward protecting accumulated wealth and generating sustainable income.
Your age does not automatically determine what you should invest in. Instead, each stage of life brings different financial goals, responsibilities and time horizons, and your investment strategy can evolve accordingly.
Your 20s: The Beginning of Your Investment Journey
Your 20s can be one of the most important stages for developing financial discipline.
At this stage, your income may be relatively modest, and you may still be building your career. You might be changing jobs, pursuing higher education, starting a business or exploring different career opportunities.
Because your responsibilities may be relatively lower than they could be later in life, this can be an opportunity to establish a strong financial foundation.
The first step does not necessarily have to be investing a large amount of money. It can simply be learning to manage your income.
Suppose you earn ₹40,000 a month. Instead of waiting until your salary becomes ₹1 lakh before starting to invest, you could begin with an amount that fits comfortably within your current budget.
The amount can increase as your income grows.
This is where the power of consistency becomes important.
Imagine two people. One starts investing at 25 but begins with a relatively small amount. The other waits until 35 because they believe they need a higher salary before starting.
The second person may eventually invest more money every month, but the first person has something valuable on their side: time.
Long-term investing allows returns to potentially generate further returns, which is commonly referred to as compounding. However, compounding does not guarantee profits, and investments can lose value, particularly over shorter periods.
Your 20s can therefore be less about finding the perfect investment and more about developing the habit of saving, investing and increasing your contributions over time.
At the same time, building an emergency fund is important. An emergency fund can help you deal with unexpected expenses without being forced to sell long-term investments at an inconvenient time.
Your 20s are also a good time to understand basic financial concepts such as equity, debt, mutual funds, diversification, risk and asset allocation.
The goal is not to become an expert overnight.
The goal is to become financially aware before your financial responsibilities become more complicated.
Your 30s: When Financial Responsibilities Begin to Grow
Your 30s can look very different from your 20s.
Your salary may have increased, but so may your responsibilities.
You may be thinking about marriage, buying a house, supporting parents, planning for children or building a larger financial cushion.
Suddenly, investing is no longer only about creating wealth for the distant future.
You may have several goals operating at the same time.
This is where goal-based investing becomes useful.
Instead of looking at your entire portfolio as one large investment bucket, think about why you are investing.
Money required within a short period may need a different approach from money intended for retirement decades later.
For example, if you are saving for a goal that is only a few years away, taking substantial market risk with that money may expose you to losses at the wrong time. On the other hand, money intended for a much longer-term goal may have a greater capacity to withstand short-term market fluctuations, depending on your risk tolerance.
Your 30s can also be a stage where you gradually increase your investment contributions.
Suppose you started investing ₹5,000 a month in your 20s. After several salary increases, you may have greater capacity to invest. Instead of allowing your lifestyle expenses to absorb the entire increase in income, you could direct part of the additional income toward investments.
This creates a simple principle:
As your income grows, allow your investments to grow with it.
Your 30s are also a stage when insurance becomes particularly relevant if other people depend on your income.
Investments are designed to help build wealth, while insurance can help protect your financial plan from certain major risks.
The combination of investing, emergency savings and appropriate insurance can create a stronger financial foundation.
Your 40s: From Wealth Creation to Wealth Planning
When you enter your 40s, retirement may no longer feel like a distant event.
You may still have many working years ahead, but the amount of time available to build your retirement corpus is shorter than it was in your 20s.
This is when it becomes important to stop and ask a simple question:
Am I actually on track for my financial goals?
You can look at your current investments, expected future contributions, retirement age and estimated expenses to create a realistic picture of your financial position.
Inflation becomes particularly important when thinking about long-term goals.
An expense that costs ₹50,000 today may cost considerably more in the future. Therefore, retirement planning should not simply ask how much money you need today. It should consider the purchasing power you may need in the future.
Your 40s can also be a good time to review your asset allocation.
Over the years, your portfolio may have become complicated. You may have accumulated stocks, mutual funds, fixed deposits, insurance products, property and other investments.
The question is no longer simply whether you own investments.
The question is whether all those investments work together toward your financial goals.
For example, if a large percentage of your wealth is concentrated in one company, one sector or one asset class, your overall financial position could become highly dependent on the performance of that particular investment.
Diversification can help reduce concentration risk, although it cannot eliminate investment losses.
This is also the stage when retirement contributions may need greater attention.
You may have competing financial priorities, but delaying retirement planning indefinitely can make the later years more financially demanding.
Your 50s: Preparing for the Next Financial Chapter

Your 50s can bring another major change in the way you look at investments.
In earlier decades, the primary question may have been:
How can I grow my wealth?
Now another question becomes equally important:
How can I use and protect the wealth I have accumulated?
Retirement may be approaching, and the time available to recover from a major portfolio decline may be shorter.
This does not automatically mean that every investment should become conservative.
Retirement can potentially last for several decades, meaning some investors may still require growth-oriented investments to help manage inflation and longevity risk.
Instead, the focus can shift toward creating an appropriate balance between growth, stability and liquidity.
Suppose you have accumulated ₹1 crore for retirement.
Having ₹1 crore is not the end of the planning process.
You also need to consider how that money will support your expenses after you stop working.
Will you receive a pension?
Will you have rental income?
How much will you need each month?
How will healthcare expenses be handled?
How much of your portfolio should remain invested for long-term growth?
These questions become increasingly important as retirement approaches.
Your 50s can therefore be a time to move from simply building a corpus toward designing a retirement income strategy.
Your Investment Strategy Should Not Be Based on Age Alone
Although age is an important consideration, it should not be the only factor determining your investment strategy.
Two people who are both 40 can have completely different financial situations.
One may have a high income, no debt, substantial savings and a paid-off home.
Another may have a home loan, children's education expenses and limited savings.
Their investment strategies may therefore need to be different.
This is why a better way to think about investment planning is through several factors working together.
Your age matters because it affects your time horizon.
Your income matters because it determines your ability to save and invest.
Your financial goals matter because different goals have different deadlines.
Your risk tolerance matters because not every investor can emotionally or financially withstand the same level of market volatility.
Your existing wealth matters because someone with substantial assets may have a different capacity for risk than someone whose entire financial future depends on a small portfolio.
Therefore, there is no universal portfolio that is automatically correct for everyone in their 20s, 30s, 40s or 50s.
The Role of Asset Allocation Throughout Your Life
Think of asset allocation as the architecture of your investment portfolio.
Instead of putting all your money into one type of investment, you divide it among different asset classes based on your goals and risk tolerance.
Equity may provide long-term growth potential but can experience significant fluctuations.
Debt and fixed-income investments can play a role in stability and income, although they also carry risks such as interest-rate and credit risk depending on the instrument.
Gold can serve as another asset in a diversified portfolio, while cash and liquid investments can provide accessibility for short-term requirements.
The balance between these assets can change as your financial circumstances change.
A young investor with a very long-term goal may have a greater capacity for market volatility than someone who needs the money within a few years.
But age alone should never be treated as a complete investment formula.
A Story of One Investor Across Four Decades
Consider someone named Ananya.
At 25, Ananya gets her first major job.
She has no children, no home loan and relatively few financial responsibilities. Instead of waiting for the perfect salary, she starts investing a small amount every month and builds an emergency fund.
At 32, her salary has increased.
Her priorities have changed too.
She is now planning for a home and thinking about her family's future. She continues investing but begins separating her investments according to different financial goals.
At 41, retirement starts appearing on her financial calendar.
She reviews her investments and realises that simply investing every month is not enough. She needs to know whether the amount she is investing can realistically support her retirement goals.
She reviews her portfolio, increases her contributions as her income allows and checks whether her investments remain aligned with her risk tolerance and time horizon.
At 52, her perspective changes again.
She is no longer thinking only about accumulating wealth.
She begins planning how her accumulated corpus could generate income after retirement. She considers healthcare costs, liquidity and how much risk she can reasonably take with money she may soon need.
Her investments changed throughout the journey.
But the most important thing remained the same.
She kept adjusting her financial strategy as her life changed.
That is the essence of life-stage investing.
The Biggest Mistake Is Treating Investing as a One-Time Decision
Many people think investing means selecting an investment and leaving it untouched forever.
But your financial life is constantly changing.
Your salary changes.
Your expenses change.
Your family changes.
Your goals change.
Markets change.
Even your ability to tolerate risk can change.
Therefore, investment planning should be viewed as an ongoing process rather than a one-time decision.
A portfolio that made sense when you were 28 may not have the same purpose when you are 45.
This does not mean constantly buying and selling investments.
It means periodically reviewing whether your strategy still matches your financial objectives.
What Should You Do When Your Income Increases?

Imagine your salary increases by ₹20,000 per month.
One option is to increase your lifestyle expenses by the entire amount.
Another approach is to divide the additional income between lifestyle improvement, financial goals and investments.
This is where lifestyle inflation can become important.
There is nothing wrong with enjoying a higher income. The problem arises when every salary increase is immediately converted into higher recurring expenses.
If your income grows but your investment contribution remains unchanged for years, your wealth-building potential may not grow at the same pace.
Increasing investments gradually as income increases can help align your lifestyle with your long-term financial goals.
What Happens When You Approach Retirement?
As retirement approaches, the purpose of your portfolio may change.
During your working years, you may primarily focus on accumulation.
After retirement, you may need to focus more on income generation and managing withdrawals.
This is why retirement planning should start well before retirement.
You have more time to identify gaps, increase contributions and make adjustments when necessary.
Waiting until the final few years can leave less room to respond if your retirement corpus is below your expectations.
Final Thought
Your investment journey is not a straight line.
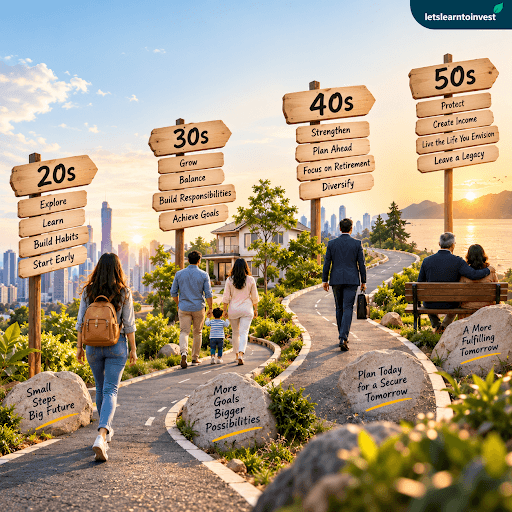
In your 20s, you may be building financial habits.
In your 30s, you may be balancing wealth creation with growing responsibilities.
In your 40s, you may be focusing more seriously on retirement and long-term financial security.
In your 50s, you may be preparing to convert years of accumulated wealth into a sustainable source of income.
The important lesson is not that everyone should follow the same investment strategy at the same age.
It is that your investment strategy should evolve as your life evolves.
Starting early, investing consistently, understanding risk and reviewing your financial goals can help create a more structured approach to long-term wealth building.
Because investing is not simply about asking, “Where should I invest my money?”
The better question is:
“What role does this money need to play in my life, and how should my investment strategy change as that role changes?”
Frequently Asked Questions
1.What is an investment strategy for different life stages?
An investment strategy for different life stages is a financial approach that changes according to your age, income, financial goals, responsibilities, time horizon and risk tolerance. The strategy used during your 20s may therefore differ from the strategy used during your 50s.
2.Should someone in their 20s start investing for retirement?
Starting early can give long-term investments more time to potentially benefit from compounding. The amount invested can be adjusted according to income and other financial priorities.
3.What should investors focus on in their 30s?
Investors in their 30s may need to balance long-term wealth creation with responsibilities such as housing, family expenses, children's education and insurance. Goal-based investing can help organize these priorities.
4.Why does retirement planning become important in your 40s?
As retirement gets closer, there is less time to build the required corpus. Reviewing existing investments, expected expenses, future contributions and asset allocation can help investors understand whether they are progressing toward their retirement goals.
5.Should investors become completely conservative in their 50s?
Not necessarily. Retirement may last for many years, so completely eliminating growth-oriented investments may expose a portfolio to inflation risk. The appropriate balance depends on the individual's goals, income requirements, risk tolerance and time horizon.
6.Is age enough to decide how much equity someone should hold?
No. Age is only one factor. Financial goals, investment horizon, income, existing assets, liabilities and risk tolerance should also be considered.
7.How often should an investment portfolio be reviewed?
A portfolio can be reviewed periodically and whenever there is a major change in income, family responsibilities, financial goals, debt or investment horizon. The purpose of reviewing is to ensure that the strategy remains aligned with the financial plan rather than making unnecessary changes.
8.Can the same investment strategy work throughout life?
A broad investment philosophy may remain consistent, but the allocation and priorities can change. The strategy that suits someone with decades before retirement may not suit someone who expects to start using their investments soon.

